

Rate: Home, Finance & Wellness

- 239.00 Reviews
- 4.5
- Downloads
- 500,000+
Our take on Rate: Home, Finance & Wellness from Appgk
Rate: Home, Finance & Wellness is a finance app from Guaranteed Rate, Inc that brings several money-related services into one mobile experience. I approached it less like a simple mortgage calculator and more like a starting point for people comparing borrowing options, planning a home-related decision, or looking for a broader collection of financial and lifestyle tools. Its store summary covers mortgages, refinancing, auto loans, home equity, personal loans, travel, and wellness, so the app is clearly aiming to be useful beyond one loan type.
My first impression is that its appeal depends on how much of your financial life you want to explore in one place. If you are already thinking about buying a home, refinancing, borrowing against home equity, or comparing a personal loan, having those paths together can reduce the need to jump between unrelated apps. If you only need a basic budget tracker or a standalone calculator, however, this is probably more than you need. The experience makes the most sense when a real borrowing decision is on your horizon.
How Rate feels during everyday use
Speed expectations when checking financial options
The first thing I noticed with a finance app like this is that perceived speed is not only about how quickly screens appear. It is also about how quickly I can understand what to do next. Rate: Home, Finance & Wellness presents a broad group of services, so the opening experience can feel more like a doorway into several conversations than a single-purpose tool. That is useful when I am still deciding whether I need a mortgage, refinance, auto loan, home equity option, or personal loan, but it can feel less direct when I already know exactly what I want.
For a quick check, I would expect the app to be most comfortable when I use it in short sessions: open it, choose the relevant borrowing path, review the information presented, and leave with a clearer next step. I would not treat it as a replacement for a full lending consultation. A mobile interface can help me organize questions and begin an application journey, but the important work still involves reviewing terms carefully and providing accurate personal and financial information.
Best Parts of Rate: Home, Finance & Wellness
Things to Keep in Mind About Rate: Home, Finance & Wellness
A useful habit is to open the app before I start collecting documents, not after. That lets me understand which loan category fits my situation and avoid entering the same information into several unrelated tools. For example, someone moving from renting to buying may begin with mortgage information, then realize that home equity is irrelevant because they do not own a property yet. That simple distinction can save time and prevent a confusing comparison.
What happens during heavier use
The heavier moments are likely to come when I move between several financial topics in one sitting, rather than when I simply browse. Comparing a refinance with a home equity option requires more concentration than checking a general overview. I also need to pause and verify whether I am looking at an educational explanation, an estimate, or a step toward an actual lending process. That difference matters because a fast-moving screen can create false confidence if I mistake an early figure for a final offer.
News and Features Related to Rate: Home, Finance & Wellness

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
I found the broad scope helpful for planning a conversation. A homeowner considering renovations, for instance, may look at home equity information while also thinking about whether refinancing makes sense. Those choices are not interchangeable, and the lower apparent monthly payment is not automatically the better financial outcome. I would use the app to frame the comparison, then check the full costs, repayment period, and effect on my wider budget before making a decision.
There is also a practical trade-off in having travel and wellness included alongside borrowing topics. These additions may make the app feel more like a general lifestyle companion, but they can distract from a time-sensitive loan task. My advice is to decide what I came to do before opening it. If I am preparing for a mortgage discussion, I would ignore the extra sections until that task is finished. This small bit of discipline keeps a wide app from becoming a source of financial browsing without a clear outcome.
Don't want to read the full review?
Reliability and recovering from interruptions
Reliability in finance is more than avoiding crashes. I also want confidence that I can return to an unfinished task without losing track of where I was. When using Rate: Home, Finance & Wellness for a serious decision, I would avoid assuming that an interrupted session has preserved every detail. If I receive a call, switch networks, or close the app while entering information, I would reopen it and review the current screen before continuing.
That is not a criticism unique to this app; it is a sensible precaution for any financial service. The cost of rechecking a form is small compared with submitting an incorrect income figure, property detail, or loan purpose. I would also keep my personal notes separately while comparing choices. A short record of the option I viewed, the questions I still have, and the documents I need can make recovery much easier if I have to stop midway.
Screenshots
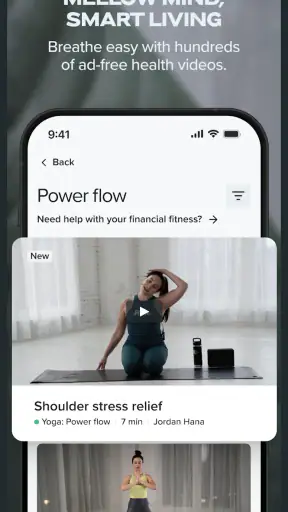
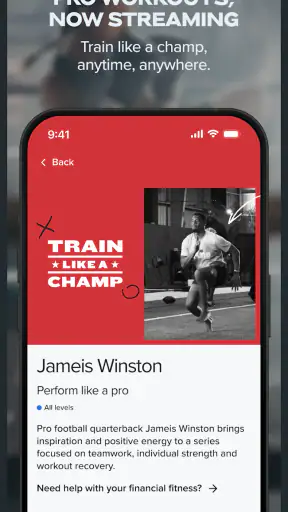
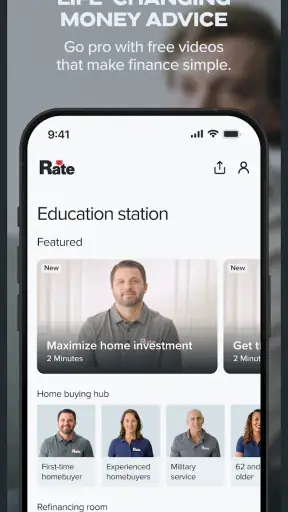
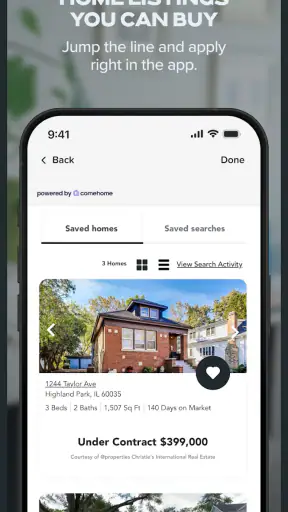
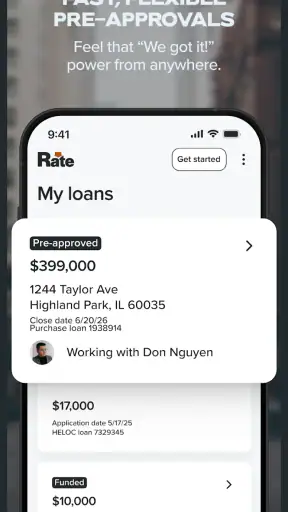
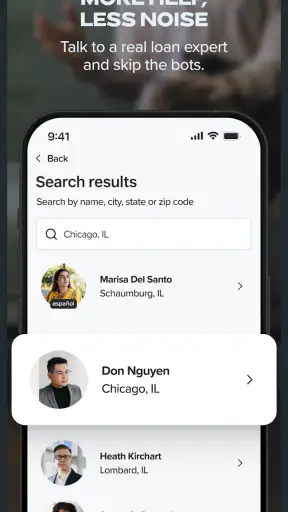
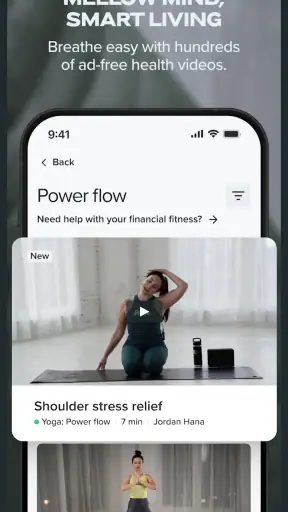
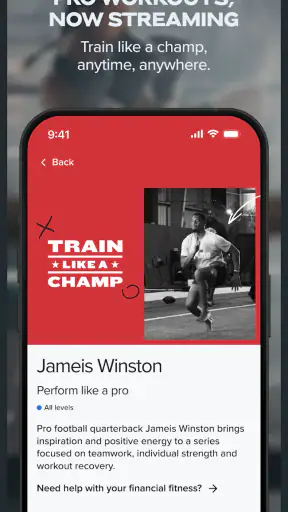
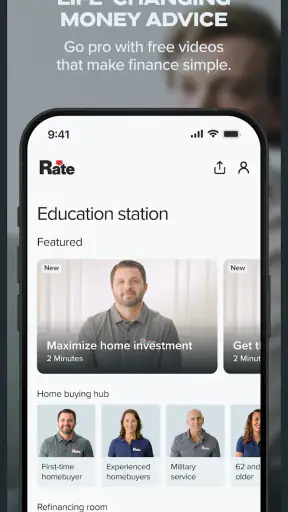
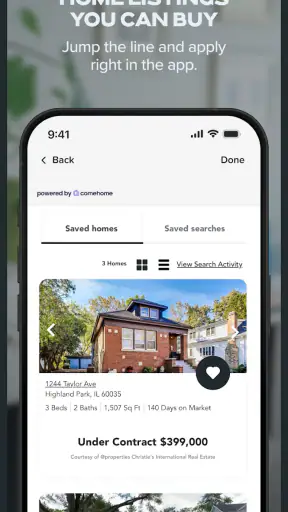
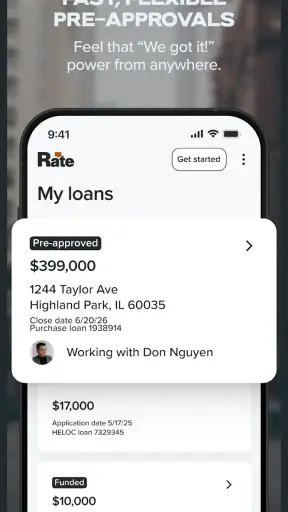
Its public reception gives me some reassurance that the app is not an obscure experiment. It has an average rating of 4.5 from around 1.9 thousand ratings, with more than 500 thousand installs. Those figures suggest that many people have tried it, but they do not guarantee that every device, network, or lending situation will feel identical. I read that kind of response as a reason to try the app, not as a substitute for checking whether it suits my own workflow.
Device constraints and practical setup
The minimum operating-system requirement is Android 7.0, which gives the app a reasonably broad reach among Android users. The current version is 1.52-prod, so I would still keep the phone updated where possible and make sure there is enough free storage for normal app updates. I would not install a finance app on a device that is already unstable or nearly full, because slow general performance can make it difficult to tell whether the problem comes from the app or the phone.
Screen size can also affect comfort. Financial forms and comparisons benefit from room to read labels, warnings, and explanatory text without rushing. On a small or older handset, I would rotate less, zoom carefully, and review each field before moving forward. A larger display is especially helpful when I am comparing loan categories or reading longer explanations, while a modern phone should make short review sessions feel more natural.
Battery demand is difficult to judge from the app’s category alone, and I would not expect a finance tool to behave like a game or a video editor. My practical approach is simple: use it when the phone has a comfortable charge, especially if I am completing a longer form away from home. The app’s value comes from accuracy and clarity, so avoiding a rushed session caused by a low battery is more important than squeezing in one more task.
A realistic mortgage-planning scenario
Imagine I am renting now, saving for a home, and unsure whether I should begin with a mortgage conversation or simply keep researching. I would open the app to explore the mortgage path, note the questions it raises, and then compare those questions with my actual budget. I might need to think about the deposit, monthly payment comfort, existing debts, and how stable my income is. The app can help me start that process, but it cannot decide what I can safely afford.
If I already own a home and want to reduce monthly pressure, I might instead investigate refinancing. In that situation, I would be careful not to compare only the payment shown on screen. The length of the new loan, closing costs, and the total amount repaid can change the result. I would use Rate as an organizing tool: identify the relevant route, prepare my questions, and then request enough detail to make a proper comparison.
For an auto or personal loan, the workflow is similar but the context changes. I would first decide whether the purchase is necessary and whether the payment fits alongside housing, utilities, insurance, and savings. The convenience of seeing several borrowing categories in one app can make comparison easier, but convenience should not encourage me to apply for credit casually. A clear purpose and a written budget should come before tapping through any serious application step.
Where the app is stronger than usual alternatives
The most obvious alternative is a collection of separate lender websites, calculators, and lifestyle apps. That approach may offer more specialized detail in each area, but it also creates friction. I have to remember which site showed which estimate and repeat background information as I move from mortgage research to refinancing or another type of loan. Rate’s advantage is the shared starting point and the possibility of keeping related decisions in one branded environment.
It also differs from a traditional budgeting app. A budget tracker is usually strongest at recording spending, categorizing transactions, and monitoring cash flow. Rate is more relevant when I am considering borrowing or a major home decision. I would not choose it as my only tool for everyday expense management unless its available tools genuinely match that need. For many people, the best combination may be a dedicated budget app for ongoing spending and Rate for loan research.
Compared with a bank’s mobile app, Rate may feel more focused on lending choices rather than daily account management. Someone who wants balances, transfers, bill payments, and card controls will probably prefer their bank’s app. Someone who wants to investigate mortgage, refinance, home equity, auto, or personal-loan directions may find Rate more relevant. The right choice depends on whether the task is managing money already held or exploring a new financial commitment.
Three less obvious ways to use it well
First, I would use the app as a question-building tool rather than a decision machine. Before contacting a lender, I can write down which loan category seems closest to my situation and identify the terms I do not understand. This makes a later conversation more productive and reduces the chance that I focus only on the most attractive headline figure.
Second, I would separate browsing from applying. A quiet session for learning about mortgages or home equity is different from a session in which I submit personal details. Keeping those activities mentally separate helps me slow down at the point where accuracy matters most. It also makes it easier to stop if I realize that I need documents or advice before continuing.
Third, I would use the app to compare purpose, not just product names. A homeowner planning repairs may be tempted to choose whichever route sounds simplest, but a home equity option and a refinance can affect the household differently. Looking at the reason for borrowing first helps me avoid selecting an option merely because it appears near the top of a menu.
These workflows are more valuable than casually opening every section. The app’s wide coverage is useful only when I give it a clear job. Otherwise, the combination of financial, travel, and wellness areas may make the experience feel broader than necessary for a single urgent decision.
Who should use it and who should skip it
I think Rate: Home, Finance & Wellness is a good fit for people at the beginning or middle of a borrowing journey. First-time home buyers may appreciate having a recognizable place to begin mortgage research. Existing homeowners comparing refinancing and home equity may also benefit from a focused starting point. It can be useful for someone who prefers mobile exploration before speaking with a lender, provided they treat the information as part of a larger decision process.
I would be more cautious recommending it to someone who only wants a simple spending tracker, a bank-account dashboard, or a specialized investment platform. Those users may find the loan-centered scope unnecessary. I would also suggest skipping it if the goal is to make a major financial decision without reading terms or asking questions. No polished mobile experience can remove the need to understand repayment obligations.
The app is free to install, and its content rating is Everyone, which makes it approachable for a broad audience. Free access is helpful when I want to explore before committing money, but it should not be confused with a cost-free loan. Borrowing decisions can involve substantial long-term expenses, so I would always move from the app’s convenient overview to a careful review of the complete terms.
My performance verdict
After looking at the app through the lens of speed, heavier use, reliability, and device demands, I see Rate: Home, Finance & Wellness as a practical launchpad rather than a complete financial command center. Its strongest quality is the way it gathers several lending paths and lifestyle topics under one roof. That can shorten the early research process, especially when I am not yet sure whether a mortgage, refinance, home equity, auto, or personal-loan route is the relevant one.
The main friction comes from that same breadth. A focused calculator or bank app can feel faster because it asks me to do one thing. Rate asks me to choose among several directions, so the experience rewards a deliberate approach. I would open it with a specific question, take notes, and slow down before submitting any important information.
With a 4.5 average and a free entry point, it is easy to justify trying when a home or loan decision is becoming real. I would recommend it to a friend who wants a mobile place to begin researching borrowing options, especially if they value convenience over highly specialized tools. I would not recommend relying on it alone for affordability, budgeting, or final financial judgment.
My final view is that Rate works best as a calm first step toward a serious conversation, not as a shortcut around one. It should feel manageable for short research sessions on supported Android devices, and its broad selection gives it a useful role between casual browsing and formal lending discussions. Used with a written budget, careful comparisons, and a willingness to verify every important detail, it can make the early stages of a major financial decision more organized.
Rate: Home, Finance & Wellness FAQ
What is Rate: Home, Finance & Wellness, and what can I use it for?
Rate: Home, Finance & Wellness is designed as a personal organization and lifestyle app that brings several everyday areas into one place. Depending on the features available in your version, you can use it to monitor home-related information, keep track of financial goals or expenses, and record wellness habits. Its main appeal is convenience, although users should review the available tools carefully because the exact functions may vary by region, subscription plan, and app updates.
Is Rate: Home, Finance & Wellness free to download and use?
The application may be free to download, but some tools, advanced features, or personalized content can require in-app purchases or a recurring subscription. Before creating an account or starting a trial, check the pricing page shown in the app and read the renewal conditions carefully. If a free trial is offered, confirm its duration and cancel it through your Google Play or App Store settings before renewal if you do not want to continue.
Does Rate: Home, Finance & Wellness protect my personal and financial information?
Because this type of app may involve household details, financial information, wellness records, or account credentials, privacy should be considered before use. Review the developer’s privacy policy to understand what data is collected, why it is used, and whether it is shared with third parties. Avoid entering highly sensitive information unless it is necessary, and use a strong password, device lock, and any available biometric or two-factor security options.
Can I rely on Rate: Home, Finance & Wellness for financial or health decisions?
You should treat Rate: Home, Finance & Wellness as an organizational and tracking tool rather than a replacement for a financial adviser, doctor, or other qualified professional. Information entered into the app may depend on your own records and may not reflect current account balances, market conditions, or medical circumstances. Always verify important financial figures independently and consult a professional before making significant money, health, or lifestyle decisions.
Will Rate: Home, Finance & Wellness work without an internet connection?
Offline functionality depends on the specific feature and how the application stores and synchronizes information. Some basic entries or previously loaded content may remain accessible without an internet connection, while account synchronization, cloud backups, updates, or connected financial services generally require mobile data or Wi-Fi. If reliable access is important to you, test the app in airplane mode after installation and confirm that your information is saved correctly once you reconnect.











